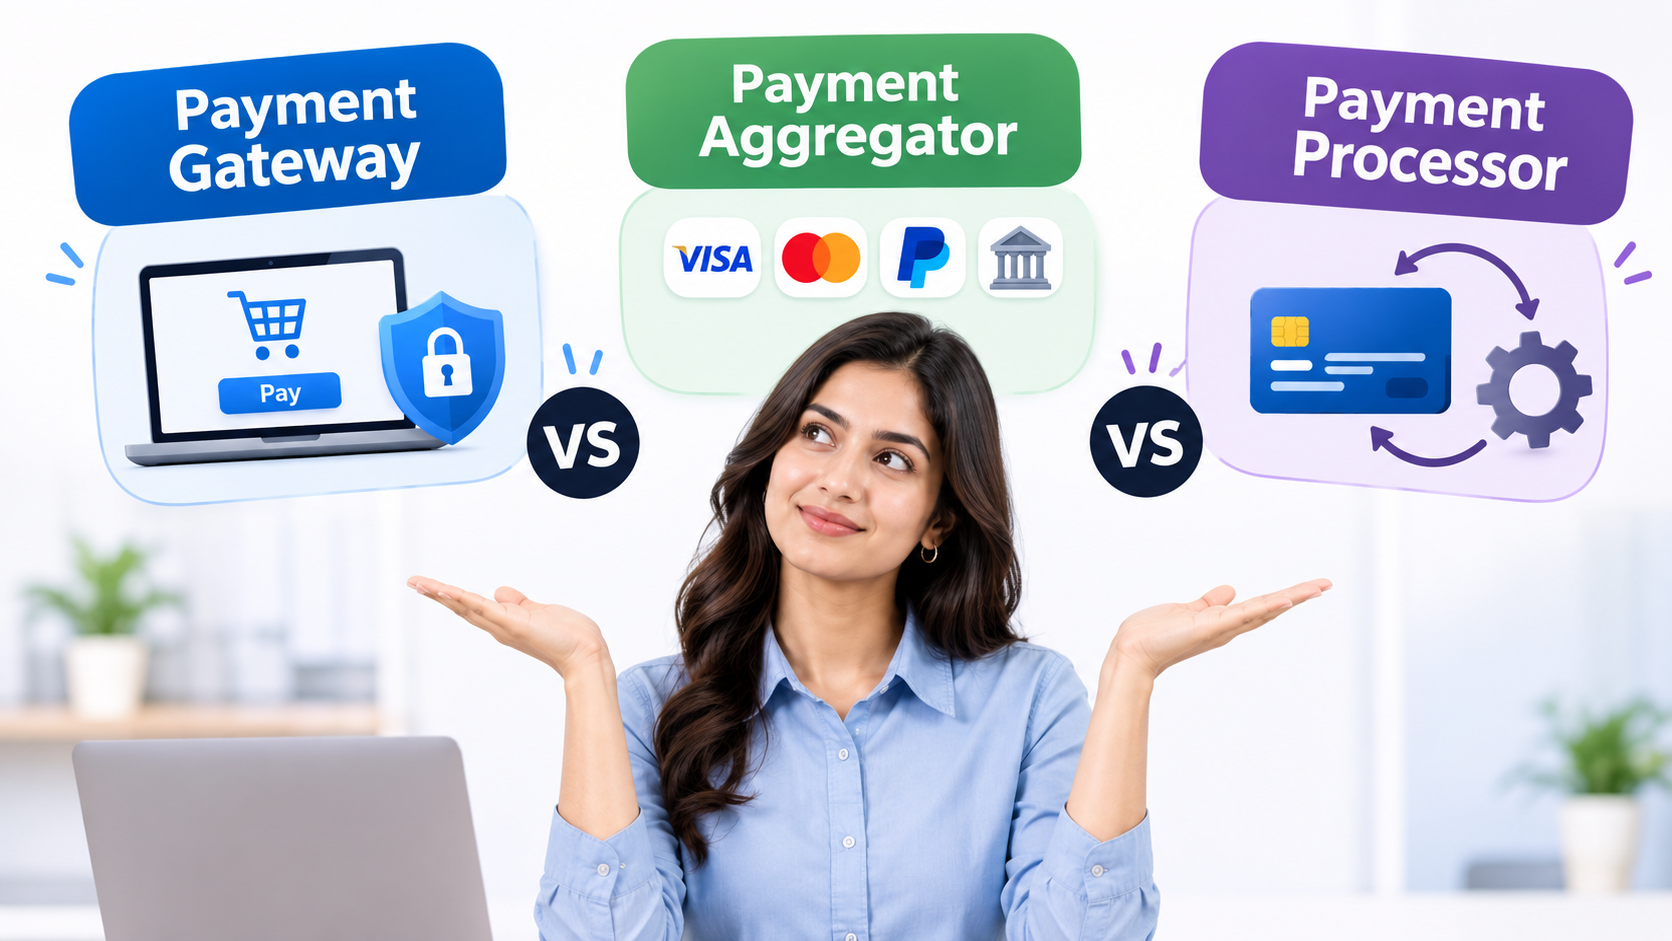
How to Start Accepting Online Payments in 2027


Imagine a customer is ready to buy from your business. But when they reach checkout, they can’t find their preferred payment method. So, they leave without buying.
You may have the right product and interested customers, but if you don’t offer the payment options they prefer, you could lose sales.
Many businesses face this problem because they set up payments once and never check their customers' needs. The good news? Learning how to accept payments online is easier than you think.
In this guide, you’ll learn how to choose the right payment provider, offer popular payment methods, and start accepting online payments without unnecessary delays or costs.
Pick Your Setup: Payment Provider, Merchant Account, or Both?
To get paid online, you need a way to accept payments from customers. How you set this up decides how fast you can start and how much each sale costs you. There are three options. Below, we explain each one in simple terms so you can pick the right one.
1. An all-in-one payment provider
You sign up online, add a checkout to your site, and start taking payments. The provider handles the bank side for you. This is the fastest way to start, and it suits new stores, small businesses, and anyone testing an idea.
2. Your own merchant account
A merchant account is a bank account made just for your business to receive card payments. Before applying, businesses should understand how to set up a merchant account for an online business and what providers require during onboarding. It takes longer to open because the bank checks your business more closely. Here, you get more control, and each sale can cost less once you are selling in large numbers.
3. Both together
Many growing businesses use an all-in-one provider and a merchant account side by side. If one stops working, the other keeps your sales going. This is also a good way to support more countries.
How do you decide? If you are just launching, start with an all-in-one provider. If your sales are steady and growing, look into your own merchant account. If you sell in several countries, or in an industry that is harder to approve, plan for more than one provider from the start.
Before you choose, write down what you sell, where your customers live, and how much you expect to process each month. Providers use these three details to decide whether to approve you.
Choose How Customers Will Pay
Once your setup is ready, you need to decide how customers will pay you. People like to pay in different ways, and if their favourite method is missing, many will leave without buying. This section covers the main payment methods to offer in 2027 and how to match them to your customers’ countries.
Best Ways to Accept Online Payments in 2027
The best ways to accept online payments depend on your customers, but five methods cover most businesses.
1. Cards: Credit and debit cards are still the most common choice in many countries, and most customers expect to see them at checkout.
2. Digital wallets: Wallets such as Apple Pay, Google Pay, and PayPal let customers pay with a tap and without typing card details. This makes checkout faster and feels safer to many buyers.
3. Pay by Bank: The customer pays straight from their bank account. This is often faster and cheaper for the business. Pay by Bank is growing in Europe because it is fast, cheap, and easy to use.
4. Direct debit: Regular payments are taken from the customer’s bank account. This works well for subscriptions and repeat billing.
5. Local payment methods: These are payment types that are popular in one country. You may need them to sell there.
If you are just starting, offer cards and one or two wallets. If your customers are in Europe, or you charge the same people every month, add Pay by Bank or direct debit.
The Cheapest Way to Accept Online Payments
The cheapest way to accept online payments is not always the provider with the lowest headline fee. You need to look at the full cost, because the money leaves in several places:
- Processing fees
- Currency conversion
- Chargeback fees
- Other fees
Once you know where the costs come from, these three steps help you save more.
- Compare the full price: Ask every provider to list all fees in writing. One low number can hide extra charges.
- Offer lower-cost payment methods: Merchants like the lower cost of bank-to-bank payments. Adding Pay by Bank or direct debit can lower your average fee.
- Avoid extra conversions: Take payments in your customer’s currency, and keep the money in that currency if you can.
Keep chargebacks low: Each chargeback costs you a fee. Fewer chargebacks mean lower costs.
Check your pricing as you grow: Most providers charge a flat rate, which is the same percentage on every sale. This is fine when you are small. When your sales grow, ask your provider if there is a cheaper plan.
Don’t choose on price alone: A low fee is no help if the provider freezes your account or holds your money for weeks. A reliable provider with fair pricing is usually the better choice.
Accepting Payments in Multiple Currencies
Selling in more than one currency makes buying easier for customers abroad. People trust a price they understand, and they are more likely to complete the purchase. To do this well, you need two things:
- Local currency payments: Customers pay in their own currency, so they avoid surprise charges on their card.
- A multi-currency account: You can hold euros, dollars, or pounds without converting each time, and you choose when to convert, ideally at a fair rate.
If you sell in Europe, a European IBAN account lets you use SEPA payments. SEPA makes euro payments across many countries simple and low-cost.
Not every provider offers multi-currency or IBAN accounts. FirmEU can connect you with partners that do, so you can match the account to the countries you sell in.
Remember that every conversion adds a cost. The fewer times your money has to change currency, the more of it you keep.
Get Approved and Keep Your Account Safe
Many new businesses get stuck at approval. Providers check who you are and what you sell before they let you take payments. This section explains how to pass those checks and keep your account safe.
How to Get Approved the First Time
Before a provider lets you take payments, they must check who you are and what you sell. These checks are called KYC (know your customer) and KYB (know your business). The provider makes the final decision, so your best move is to arrive well prepared.
You will usually need these documents:
- Company registration papers and ID for the owners and directors
- Proof of your business address and recent bank statements
- A clear description of what you sell, who your customers are, and your expected monthly sales
Your website matters just as much as your documents. It should show clear product or service descriptions, prices, a refund and cancellation policy, your contact details, and your terms and privacy policy.
Most rejections come from simple, avoidable problems. Details may not match between your documents and your website. The site may look unfinished. There may be no refund policy, the business category may be wrong, or you may have a history of many chargebacks.
Before you apply, compare every document with your website, because small mismatches cause many delays. Be honest about what you sell as well. A provider that finds a surprise later is far more likely to close your account.
What If You’re Considered High-Risk?
Some businesses are seen as higher risk by banks and providers. This does not mean they are doing anything wrong. It means customers in that industry tend to dispute payments more often.
Common examples are crypto, adult content and dating, CBD, gambling and gaming, travel, and subscription businesses. Businesses accepting digital asset payments can explore crypto payment processing solutions designed for this industry.
Standard providers often decline these businesses, or approve them and close the account later. If this applies to you, these steps help:
- Choose providers that support your industry: They already understand your risks and are more likely to approve you.
- Prepare a stronger application: Include licences, policies, and a clear explanation of how you handle refunds and disputes.
- Set up a backup provider: One problem with a single provider should not stop all your sales.
Expect extra checks, and know that some providers hold back a portion of your sales as a reserve. The hardest part is usually knowing which providers will say yes, and that is where a matching service can save time. We cover this at the end of the guide.
Reduce Failed Payments and Chargebacks
A failed payment is a lost sale, and a chargeback is a lost sale plus a fee. The good news is that both can be reduced once you know the causes.
Payments usually fail because the customer typed a detail wrong, their bank flagged the payment as risky, the processor had a temporary problem, or the card had no funds or had expired.
Three fixes make the biggest difference:
- Use a clear billing name. If the name on the card statement does not match your brand, customers may not recognise the charge and may dispute it.
- Add security checks. Tools such as 3D Secure and fraud screening block bad payments without bothering good customers.
- Use a backup processor. If one route fails, the payment can try another. This is called payment cascading to reduce failed transactions.
Refunds and disputes need attention too. Make refunds easy, because a customer who gets a quick refund is less likely to call their bank. Keep order records, delivery proof, and customer messages ready so you can answer disputes fast.
Where you can, offer instant refunds, since customers increasingly expect instant refunds as Pay by Bank and instant bank payments grow.
Finally, check your chargeback rate every month. If it climbs, providers may raise your fees or close your account, so fix problems early.
Not Sure Which Provider Fits? FirmEU can Help
Choosing the right bank or payment provider takes time, especially if you sell in many countries or work in an industry that is harder to approve. Applying to the wrong provider can mean weeks of waiting and a rejection at the end.
FirmEU is an independent matching service that helps businesses explore suitable payment processing services through its network of payment partners. You share details about your business, and FirmEU introduces you to banks and payment providers from its network of 250+ verified partners that fit your profile. It is not a bank or a payment processor, and the provider you are introduced to makes the final decision on approval and onboarding.
Conclusion
Accepting online payments in 2027 comes down to three things: the right setup, the right payment methods, and a provider that approves your business. Prepare your documents, keep your costs clear, and plan for a backup.
If you want help finding the right bank or payment provider, Get Matched with FirmEU and tell us about your business. They will introduce you to partners that fit.
All Blog Posts




Find the Right Banking and Payment Processing Partner for Your Business
Tell us about your company, and we’ll match you with the most suitable global banking or payment providers from our verified network.